Contact Your USDA Mortgage Loan Specialist: Local (717) 306-7144 | Toll Free (866) 747-2882

Speak With a USDA Loan Specialist • No AI Chatbots

Buy a Home in Pennsylvania With $0 Down

See if you qualify for a USDA home loan with no down payment. Explore income limits, eligible locations, and financing options with guidance from a licensed mortgage loan specialist.

Quick Pre-Qualification Review
No Obligation Assessment

Licensed in PA, MD, VA & WV

No obligation • Fast pre-qualification • Secure application

$0 Down Payment
Credit Scores as Low as 580
Eligible Rural & Suburban Areas
One-on-One Loan Consultation
USDA Home Loans in Pennsylvania

Explore USDA home loans in Pennsylvania for purchasing, refinancing, renovating or building a home. Discover which financing option best meets your homeownership goals.

Buy your next home with no down payment.

Learn More →

Explore options to lower your existing USDA mortgage payment.

Learn More →

Buy a home and finance improvements with one mortgage.

Learn More →

Build your new home with $0 down and one loan closing.

Learn More →

See What Our Clients Are Saying

Why Choose a USDA Home Loan in Pennsylvania?

USDA Guaranteed Home Loans help eligible Pennsylvania homebuyers purchase a home with no down payment, affordable monthly mortgage payments and flexible qualification requirements.

$0 Down Payment

Purchase an eligible home with 100% financing. No money down payment required.

Seller-Paid Closing Costs

With up to 6% in seller assistance, you may be able to close with no money out of pocket.

Flexible Credit Requirements

Financing options may be available with credit scores as low as 580, subject to approval.

Affordable Monthly Payments

Lower annual fees than mortgage insurance on many comparable FHA and Conventional loans.

30-Year Fixed Rate

Predictable principal and interest payments throughout the loan term.

No Set Loan Limit

Your borrowing power depends on repayment ability and loan eligibility.

Pennsylvania USDA Home Loan Frequently Asked Questions (FAQs)

What is a USDA home loan, and how does it work?

A USDA home loan is a government-backed mortgage designed to help eligible homebuyers purchase a primary residence in qualifying rural and suburban areas. Through the USDA Single Family Housing Guaranteed Loan Program, qualified borrowers can finance up to 100% of a property's eligible value, potentially purchasing a home with no down payment. USDA loans are offered through participating mortgage lenders and are subject to household income limits, property eligibility requirements, and borrower qualification guidelines.

Can I buy a home in Pennsylvania with no down payment?

Yes. USDA Guaranteed Home Loans offer eligible homebuyers in Pennsylvania the opportunity to purchase a primary residence with no down payment. The program provides 100% financing for qualified borrowers purchasing homes in USDA-eligible areas. Although a down payment is not required, buyers may still have closing costs and prepaid expenses. Seller concessions, lender credits, or other permitted sources of funds may help reduce the amount of money needed at closing.

Do I have to be a first-time homebuyer to qualify for a USDA loan?

No. USDA home loans are available to both first-time and repeat homebuyers. You do not need to be purchasing your first home to qualify. However, the property must be your primary residence, and USDA generally requires applicants to be unable to obtain conventional financing without a USDA guarantee. Applicants who already own a home may qualify under certain circumstances, depending on their existing housing situation and USDA requirements.

What credit score do I need for a USDA loan?

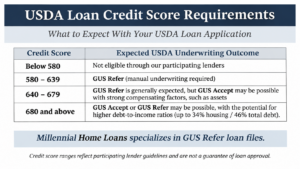
USDA does not establish a universal minimum credit score for its Guaranteed Loan Program. However, individual lenders may have their own minimum credit score requirements. A score of 640 or higher can simplify the automated underwriting process, but borrowers with credit scores as low as 580 may still qualify depending on the lender, credit history, debt-to-income ratio, and other financial factors. Mortgage approval depends on the overall strength of the application, not just the credit score.

What are the USDA income limits in Pennsylvania?

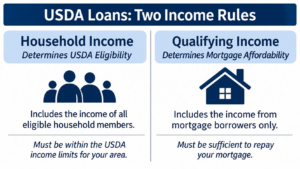
USDA Guaranteed Home Loans have household income limits that vary by Pennsylvania county and household size. Generally, the program is intended for households with adjusted annual income not exceeding 115% of the applicable area median income. USDA considers qualifying income from adult household members, even when some are not borrowers on the mortgage. Certain deductions may apply when determining eligibility.

View the current Pennsylvania USDA Income Limits by County to compare limits for all 67 counties.

How do I check if a Pennsylvania property is USDA eligible?

USDA property eligibility is based primarily on the home's location. Many Pennsylvania communities outside major metropolitan areas qualify, including some suburban locations that buyers may not consider rural. You can check a specific property's address using the official USDA Property Eligibility Map. The map provides an initial indication of geographic eligibility, but final eligibility is determined by USDA based on the property's location and applicable program requirements.

Official resource: https://eligibility.sc.egov.usda.gov/

What types of properties qualify for USDA financing?

USDA Guaranteed Home Loans can finance eligible single-family residences, certain townhomes, approved condominiums, and qualifying newly constructed homes. The property must be located in a USDA-eligible area, used as the borrower's primary residence, and meet applicable property condition and appraisal requirements. USDA loans are not intended for vacation homes or investment properties. Homes with acreage may qualify, provided the property meets USDA requirements and is not primarily an income-producing operation.

What are the employment and income requirements for a USDA loan?

USDA lenders evaluate whether borrowers have sufficient, stable, and dependable income to make their mortgage payments. Employment income, self-employment income, retirement benefits, and certain other documented income sources may be considered. Lenders review employment history, income consistency, existing debts, and the borrower's ability to repay the mortgage. USDA also evaluates total household income separately to determine whether the household falls within the program's income eligibility limits.

How much are USDA closing costs, and can the seller pay them?

USDA homebuyers may have closing costs that include lender fees, title services, appraisal expenses, recording charges, prepaid taxes, and homeowners insurance. USDA permits eligible seller concessions of up to 6% of the sales price toward allowable buyer costs, subject to program requirements. Lender credits may also help offset expenses. In certain situations, eligible closing costs may be financed when the property's appraised value exceeds the purchase price and USDA requirements are satisfied.

Does a USDA loan require mortgage insurance?

USDA Guaranteed Home Loans do not use conventional private mortgage insurance (PMI), but they do have guarantee fees that serve a similar purpose. These typically include an upfront guarantee fee, which may be financed into the loan, and an annual fee collected through monthly mortgage payments. The fees help support the USDA loan guarantee program. The applicable fee percentages are established by USDA and may change over time.

Can I buy a home that needs repairs with a USDA loan?

Yes, in certain circumstances. USDA financing may be available for properties needing eligible repairs or improvements, provided the home and proposed work meet program requirements. Some repairs may need to be completed before closing, while qualifying renovation or repair arrangements may permit work after closing under specific conditions. The extent of allowable repairs, contractor requirements, financing structure, and completion deadlines depend on the USDA program and participating lender.

How do I get pre-approved for a USDA loan in Pennsylvania?

USDA mortgage pre-approval generally begins with a review of your credit, income, employment, assets, and existing debts. A participating mortgage lender can evaluate your financial qualifications and estimate an affordable purchase price. You should also verify that the property location and household income meet USDA eligibility requirements. A pre-approval helps you understand your financing options before making an offer, although final loan approval remains subject to underwriting, property review, and other conditions.

Scroll to top
Pennsylvania County Lookup