Contact Your USDA Mortgage Loan Specialist: Local (717) 306-7144 | Toll Free (866) 747-2882
USDA Home Loans in Pennsylvania
Buy a Home in Pennsylvania with $0 Down
What Credit Score Do You Need for a Pennsylvania USDA Loan?
Pennsylvania USDA Loan Credit Score Requirements
Although USDA does not establish a universal minimum credit score, individual mortgage lenders have their own requirements. At Millennial Home Loans, we work with lenders offering USDA financing to qualified borrowers with credit scores starting at 580.
Your credit score can influence whether your application receives a GUS Accept or GUS Refer recommendation through the USDA Guaranteed Loan Program Underwriting System (GUS).
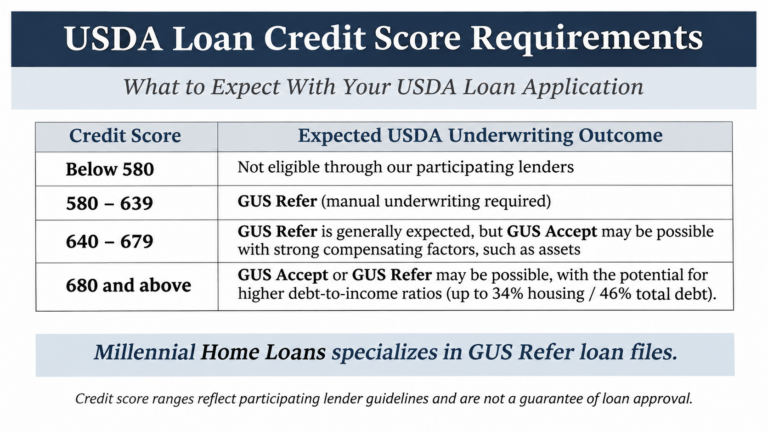
The following table summarizes what borrowers can generally expect through our participating lenders.
| Credit Score | Expected USDA Underwriting Outcome |
|---|---|
| Below 580 | Not eligible through our participating lenders |
| 580–639 | GUS Refer is the best anticipated outcome; manual underwriting required |
| 640–679 | GUS Refer is generally expected; GUS Accept may be possible with strong compensating factors |
| 680 and above | GUS Accept or Refer may be possible depending on the overall application |
What Is the Difference Between GUS Accept and GUS Refer?
GUS Accept: The automated underwriting system determines that the application meets its risk assessment standards, subject to verification and lender approval. A GUS Accept may provide greater flexibility with debt-to-income ratios.
GUS Refer: The application requires additional underwriting review, commonly referred to as manual underwriting. A Refer does not mean the loan has been denied.
In fact, the majority of USDA loans closed through Millennial Home Loans are GUS Refer files. Many qualified borrowers successfully obtain USDA financing through manual underwriting.
For GUS Refer applications, lenders strongly prefer borrowers with no credit or housing payments 30 days or more past due within the most recent 12 months.
How Do Credit Scores Affect USDA Debt-to-Income Ratios?
USDA evaluates both the proposed monthly housing payment and the borrower’s total monthly debts compared with gross qualifying income.
| Underwriting Result | Housing Ratio | Total Debt Ratio |
|---|---|---|
| GUS Refer – Standard | 29% | 41% |
| GUS Refer – Eligible Waiver | Up to 32% | Up to 44% |
| GUS Accept | Up to 34% | Up to 46% |
A GUS Refer debt-ratio waiver generally requires a minimum validated credit score of 680 for all applicants, acceptable compensating factors, and satisfaction of additional USDA requirements.
GUS Accept ratios depend on the automated findings and participating lender requirements. The 34%/46% figures shown above represent a lender-specific example, not universal USDA maximums.
Can You Qualify for a USDA Loan With a 580 Credit Score?
Yes, potentially. A borrower with a 580 credit score may qualify through participating USDA lenders, provided the borrower meets applicable credit history, income, debt-to-income, and manual underwriting requirements.
A strong recent payment history can be particularly important. Borrowers with scores below 640 should generally anticipate more detailed underwriting review.
Pennsylvania USDA loan credit score requirements vary by lender, and borrowers with lower credit scores may still qualify when they demonstrate acceptable payment history, stable income, and manageable monthly debts.
Find Out if You Qualify for a Pennsylvania USDA Loan
Your credit score is only one factor in USDA mortgage approval. Employment, income, monthly debts, and recent payment history are also important. You can also learn more about Pennsylvania USDA loan income requirements to understand how household income and qualifying income affect eligibility.
At Millennial Home Loans, we work with multiple wholesale mortgage lenders to help borrowers explore USDA financing options, including loans for qualified applicants with credit scores starting at 580.
Frequently Asked Questions About USDA Credit Score Requirements
What Is the Minimum Credit Score for a USDA Loan in Pennsylvania?
USDA does not establish a universal minimum credit score. However, Millennial Home Loans works with participating lenders offering USDA financing to qualified borrowers with credit scores starting at 580.
Can You Get a USDA Loan With a GUS Refer?
Yes. A GUS Refer does not mean the loan has been denied. It means the application requires manual underwriting. In fact, the majority of USDA loans closed through Millennial Home Loans are GUS Refer files.
Can You Qualify for a USDA Loan With Recent Late Payments?
Possibly, but recent late payments can make approval more difficult. For GUS Refer applications, lenders strongly prefer borrowers with no credit or housing payments 30 days or more past due within the preceding 12 months.
Does a 680 Credit Score Guarantee USDA Loan Approval?
No. A 680 credit score does not guarantee approval or a GUS Accept recommendation. USDA also evaluates income, monthly debts, payment history, and other financial factors before determining eligibility.
For more information, contact Millennial Home Loans at (866) 747-2882.