Speak With a USDA Loan Specialist • No AI Chatbots
BUY A PENNSYLVANIA HOME WITH $0 DOWN.
SEE IF YOU QUALIFY
Find out if your income, location, and homebuying goals qualify for a USDA Loan.
Quick Pre-Qualification Review
No Obligation Assessment
Licensed in PA, MD, VA & WV
No obligation • Fast pre-qualification • Secure application
$0 Down Financing
Credit Scores Starting at 580
Many Available Pennsylvania Areas
One-on-One Loan Consultation
Not All USDA Mortgage Loan Officers Are Created Equal
USDA Home Loans Are a Specialty. Experience Matters.
If you needed a specialized medical procedure, would you prefer to work with a general practitioner or a specialist who has years of experience performing that particular procedure?
The same principle applies when selecting a mortgage loan officer for a USDA home loan that is a USDA Loan Specialist.
Just because a mortgage company offers USDA financing does not necessarily mean that its loan officers have extensive experience with the program.
In 2025, USDA/Rural Housing Service loans represented approximately 0.6% of reported residential mortgage originations nationwide. That is roughly one out of every 175 mortgage transactions.
With USDA loans representing such a small percentage of the overall mortgage market, it is understandable that many mortgage loan officers have limited exposure to the program and its more complex underwriting requirements.
At Millennial Home Loans, USDA mortgage financing is not simply another product on our list of available loan programs. It is one of our principal areas of expertise.
USDA Mortgage Experience Dating Back to 2010
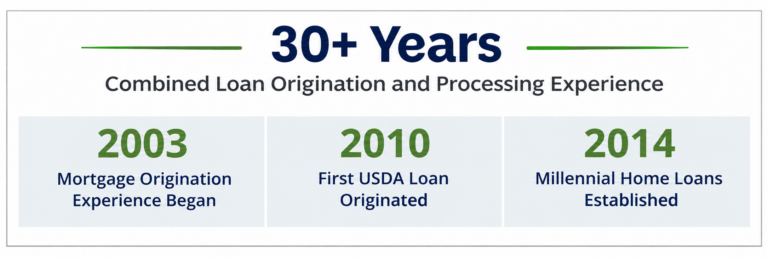
David Zuckerman, producing loan originator and owner of Millennial Home Loans, began originating residential mortgage loans in 2003 and originated his first USDA home loan in 2010, when relatively few homebuyers, real estate agents and mortgage professionals were familiar with the program.
When Millennial Home Loans was established in 2014, USDA financing was already an important part of our business.
Our years of experience working with USDA homebuyers have given us an extensive understanding of the program, its underwriting requirements and the financing opportunities available to prospective homebuyers.
We understand that originating a USDA home loan requires much more than determining whether a property is located in an eligible area.
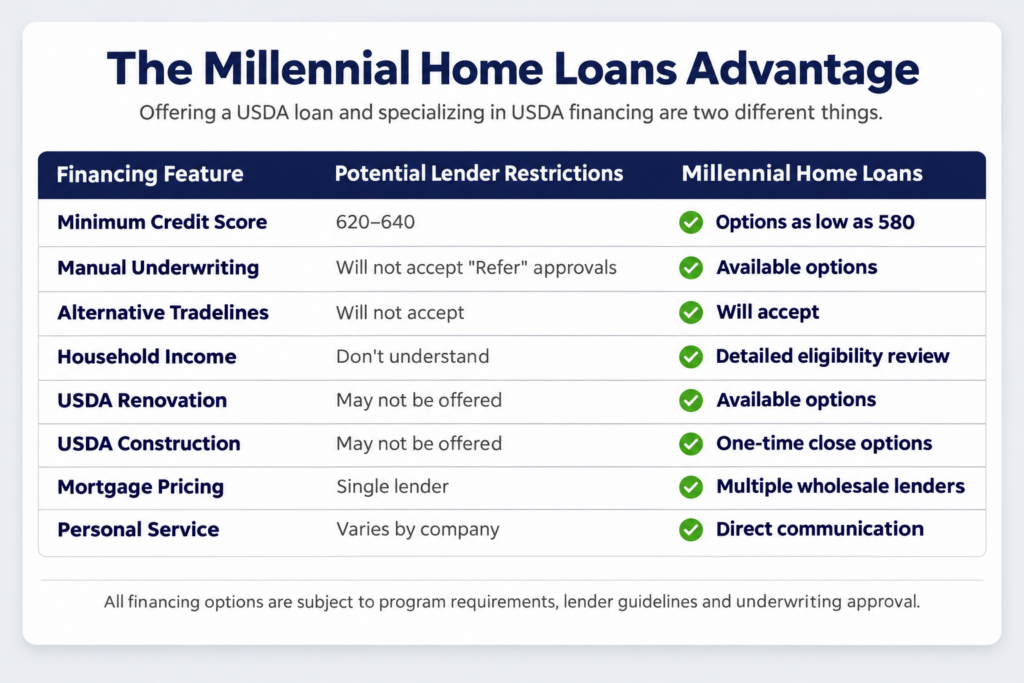
Working with a USDA Loan Specialist Helps You Get to the Finish Line
Credit Scores Below 620
The USDA Guaranteed Loan Program does not establish a universal minimum credit score. However, individual mortgage lenders frequently establish their own minimum credit score requirements.
These additional lender requirements are commonly referred to as investor overlays.
If you have been told that your credit score is too low for a USDA home loan, that may reflect the requirements of a particular mortgage lender rather than the requirements of the USDA loan program itself.
At Millennial Home Loans, we have access to USDA financing options for borrowers with credit scores as low as 580, subject to applicable underwriting requirements.
A denial from one mortgage company does not necessarily mean that you are ineligible for USDA financing.
Manual Underwriting
USDA utilizes an automated underwriting system known as the Guaranteed Underwriting System, commonly referred to as GUS.
When a loan application does not receive an automated Accept recommendation, it may require additional documentation and manual underwriting.
Some mortgage companies do not offer manually underwritten USDA loans.
At Millennial Home Loans, we understand how to evaluate these scenarios, identify applicable compensating factors and work with lenders that offer manual underwriting.
A Refer recommendation from GUS does not automatically mean that a USDA loan cannot be approved.
Non-Traditional Credit References
Not everyone has an extensive credit history consisting of credit cards, automobile loans and other conventional credit accounts.
Depending on the circumstances, eligible alternative credit references may help establish or supplement a borrower’s credit history.
These may include:
- Rental payment history
- Utility payments
- Telephone payments
- Cable and internet payments
- Other eligible recurring financial obligations
Knowing which alternative tradelines may be acceptable, how they need to be documented and which lenders will consider them is an important part of USDA mortgage experience.
We work with prospective homebuyers to identify these opportunities when applicable.
Understanding USDA Household Income Limits
One of the most frequently misunderstood aspects of USDA financing is the difference between household income eligibility and qualifying income.
Income used to determine whether a household is eligible for the USDA loan program can differ substantially from the income used to determine how much a borrower can afford.
Certain income sources may be excluded, and eligible household deductions may reduce the amount of income counted toward the applicable USDA income limit.
An accurate evaluation is particularly important for households with multiple wage earners, overtime income, dependent children, childcare expenses or other circumstances that could affect income eligibility.
Before assuming that your household earns too much to qualify, speak with someone who understands how USDA household income is calculated.
Understanding Your Maximum Purchasing Power
USDA financing is not simply a matter of applying a fixed mathematical formula to your monthly income.
Automated underwriting results, credit history, financial reserves, existing monthly obligations and applicable compensating factors may influence the amount of financing available to you.
Our objective is to help you understand your actual financing options while remaining comfortable with your anticipated monthly mortgage payment.
We believe a homebuyer should have a meaningful understanding of their purchasing power before entering into a contract to purchase a home.
Property Eligibility, Inspections and Testing Requirements
Just because a home is located within a USDA-eligible geographic area does not necessarily mean the property satisfies all USDA financing requirements.
Properties with private wells, septic systems, outstanding repairs or other unique characteristics may require additional documentation, inspections or testing.
Understanding these requirements early in the homebuying process can help prevent unnecessary delays and unexpected expenses.
Our experience allows us to help homebuyers and their real estate agents identify potential property-related financing issues before they become significant obstacles.
USDA Renovation Loans
Many homebuyers overlook properties that need repairs because they believe USDA financing is available only for homes that are already in move-in-ready condition.
Depending on the property, proposed improvements and applicable financing requirements, USDA renovation financing may allow eligible homebuyers to purchase a home and finance repairs or improvements through a single mortgage.
At Millennial Home Loans, we understand the complexities associated with renovation financing, including contractor documentation, repair budgets, inspections and construction draws.
We can help you explore financing opportunities that may otherwise be overlooked.
USDA One-Time Close Construction Loans
USDA financing is not limited to purchasing an existing home.
Eligible homebuyers may also be able to finance the purchase of land and construction of a new home through a USDA one-time close construction loan.
Construction financing introduces additional complexities involving builders, construction budgets, land ownership, appraisals and construction draw schedules.
Having access to the appropriate financing program and working with mortgage professionals familiar with the construction process can make a significant difference.
Access to Multiple Mortgage Lenders
Every mortgage lender has its own pricing, underwriting policies and program availability.
As an independent mortgage brokerage, Millennial Home Loans is not limited to the financing options of a single lending institution.
We evaluate available wholesale lending sources based on the circumstances of each individual mortgage transaction.
This allows us to consider not only mortgage pricing but also the underwriting requirements, program availability and lender capabilities that may be important to your particular situation.
We encourage prospective clients to compare our mortgage financing options with those offered by other mortgage companies.
Experience Without Sacrificing Personal Service
Millennial Home Loans is a small, independent mortgage brokerage.
We consider that one of our strengths.
When you work with us, you have direct access to experienced USDA Loan Specialists who are familiar with your individual circumstances and are actively involved in your mortgage transaction.
Some clients prefer regular telephone conversations and detailed explanations throughout the homebuying process.
Others prefer electronic communication, online applications and digital document submission, with minimal telephone interaction.
We are comfortable with either approach.
Whether you want someone to guide you through every step of the mortgage process or simply want an experienced professional available when questions arise, we adapt to your preferred level of communication.
We combine specialized mortgage knowledge, modern technology and personalized service because we believe our clients deserve all three.
Questions to Ask Before Selecting a USDA Mortgage Loan Officer
Before deciding which mortgage company you want to work with, consider asking the following questions:
- How long have you been originating USDA home loans?
- How frequently do you work with USDA homebuyers?
- What is your minimum USDA credit score requirement?
- Do you work with lenders that manually underwrite USDA loans?
- Can you assist borrowers with non-traditional credit references?
- How do you calculate adjusted household income eligibility?
- What are the requirements for private well water testing?
- Do you offer USDA renovation loans?
- Do you offer USDA one-time close construction loans?
- Do you have access to multiple USDA mortgage lenders?
- Who will I communicate with throughout the mortgage process?
The answers may reveal important differences between mortgage companies that appear to offer the same loan program.
Have You Been Told That You Don’t Qualify for a USDA Home Loan?
Before abandoning your homeownership plans or assuming that you must save for a substantial down payment, consider obtaining a second opinion.
A particular mortgage lender’s credit score requirements, underwriting restrictions or program limitations may not be representative of every USDA financing opportunity.
We cannot guarantee that every homebuyer will qualify for a USDA home loan. However, we can provide an experienced evaluation of your circumstances and explore the financing options that may be available to you.
You owe it to yourself to speak with a USDA mortgage specialist.
At Millennial Home Loans, we welcome the opportunity to earn your business.
Small by design. Personal by choice. Experienced by specialization.
Speak directly with a USDA Loan Specialist.
Call (866) 747-2882 or select Check My USDA Eligibility to get started.
No obligation. No pressure. Personalized mortgage guidance.
Source for national mortgage origination statistics: MortRadar analysis of 2025 CFPB/FFIEC Home Mortgage Disclosure Act data.